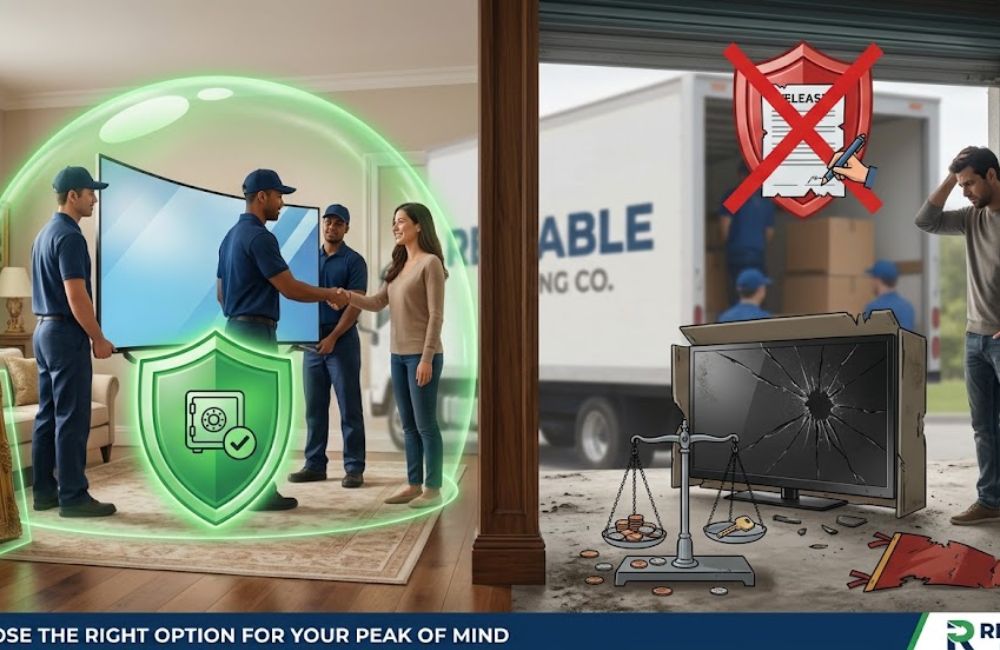
Full value protection vs. released value isn’t a question most people think about until something’s already broken. It shows up as one line on the bill of lading, usually near the end of a stack of paperwork you’re signing on moving day, and it’s easy to skim past. But that one line decides whether a damaged item gets replaced at its real value or reimbursed for pennies. At Bert Hill Moving & Storage, we walk every customer through this before moving day, not on it, because no one should make this decision while a truck is idling in the driveway.
Here’s what the two options actually mean, what they cost, and how to figure out which one makes sense for your move.
Valuation Coverage Isn’t the Same Thing as Insurance
Before comparing the two options, it helps to clear up a common mix-up: what movers offer isn’t technically insurance; it’s valuation coverage. Insurance is a separate product you’d buy from a third-party provider. Valuation is a federally regulated standard that sets the maximum amount a mover is liable to pay if something you own is lost or damaged during an interstate move. According to the Federal Motor Carrier Safety Administration (FMCSA), licensed interstate movers are required to offer two specific valuation options, and you have to choose between them in writing.
Released Value Protection: The Free Option That Rarely Covers Much
Released Value Protection is included automatically at no extra cost. The trade-off is that it values your belongings by weight, not worth. Per the FMCSA, the mover’s liability under this option is capped at 60 cents per pound, per article — regardless of what the item actually cost or means to you.
The FMCSA’s own example makes the gap obvious: a 50-inch television weighing 25 pounds that’s lost or destroyed in transit would be reimbursed at 60 cents per pound, for a total of $15 — nowhere close to what a replacement television actually costs. The same math applies to anything in your home: a laptop, a dresser, a box of kitchen equipment. Weight, not value, is what determines the payout.
Full Value Protection: What You’re Actually Paying For
Full Value Protection is the upgraded option, and under FMCSA rules, movers must repair the item, replace it, or offer a cash settlement based on its current market value if it’s lost or damaged. It typically costs extra, often priced as a small percentage of your shipment’s total declared value, and may include deductible options that lower the premium in exchange for a higher out-of-pocket cost on a claim.
Two details of Full Value Protection are easy to miss and worth confirming with your mover directly:
- You must declare high-value items separately. Items worth more than $100 per pound — jewelry, fine china, furs, and similar pieces — may not be fully covered under Full Value Protection unless you list them specifically on the shipping documents before the move.
- Boxes you pack yourself may be treated differently. Movers often limit liability on customer-packed boxes because they can’t verify how well the contents were protected before pickup. If you want full coverage on those boxes too, ask whether your mover offers professional packing services for anything you’d want fully covered.
Which One Do You Actually Need?
For a short local move of a lightly furnished apartment — a few boxes, some basic furniture, nothing especially valuable — Released Value Protection’s coverage gap might be a manageable risk, particularly if the added cost of Full Value Protection doesn’t feel proportional to what’s being moved. But for most household moves, the math usually favors the upgrade. Think through what’s actually going on the truck: a mattress, a dresser, a television, kitchen appliances, maybe a few pieces of furniture that would cost real money to replace. Run those items through the 60-cents-per-pound math, and the gap between what Released Value Protection pays and what those items would cost to replace becomes obvious fast.
Distance matters too. A move across town carries less risk of damage simply because the items spend less time in transit and change hands fewer times. A move across state lines, especially one that involves loading onto a truck, driving for days, and unloading at the other end, has more opportunities for something to go wrong — which is exactly the scenario Full Value Protection is built for.
It’s also worth asking whether your homeowner’s or renter’s insurance policy already extends any coverage to a move, since some policies do and some don’t — that’s a question for your insurance agent, not your mover. Still, it’s worth asking before you decide how much additional valuation coverage to buy.
What to Ask Before You Sign the Bill of Lading
The bill of lading is the contract between you and your mover, and it’s where your valuation choice gets locked in. Before signing, it’s worth asking:
- What exactly does Full Value Protection cost for this specific move, and is there a deductible option?
- Are there items excluded from full coverage, such as high-value pieces or customer-packed boxes?
- What’s the claims process, and how long does it typically take?
Federal law gives you nine months from delivery to file a written claim, and the mover has 30 days to acknowledge it and 120 days to resolve it — timelines worth knowing before you need them, not after.
Frequently Asked Questions About Moving Valuation Coverage
Is Full Value Protection the same as moving insurance?
No. Valuation coverage is a federally regulated liability standard set by the mover; insurance is a separate product purchased from a third-party provider. Some people choose to carry both.
What happens if I don’t choose either option?
Federal rules require movers to offer both options in writing, and you must actively choose one. If you don’t specifically select Released Value Protection, Full Value Protection typically applies by default — but this can vary by mover, so confirm it in writing before moving day.
Does Full Value Protection cover 100% of an item’s value?
It covers the item’s declared value under the mover’s plan, which may include deductibles and exclusions for high-value or customer-packed items. Ask for the written details of the plan you’re being offered.
How long do I have to file a claim if something is damaged?
Federal law gives you nine months from your delivery date to file a written claim. The mover then has 30 days to acknowledge it and up to 120 days to resolve it.
Does valuation coverage apply to local moves too?
Federal valuation rules specifically govern interstate moves. State regulations typically govern local, in-state moves, so ask your mover what coverage applies to a purely local move.
How Bert Hill Talks Through Valuation Coverage With Every Customer
We go over valuation options with every customer during the estimate, not as fine print at pickup, so you know exactly what’s covered before your things are on the truck. If your move involves a storage gap, the same questions apply to anything sitting in our on-site storage facility, and we’re happy to walk through what’s covered while your items are there, too.
We’ve been moving households throughout Western Massachusetts and Northern Connecticut since 1915, and one of the more overlooked parts of a good move is making sure you actually understand what you’re signing. If you’d like to talk through your options before your next move, get a free estimate from our team.
Sources
- Federal Motor Carrier Safety Administration, “Liability & Valuation” — fmcsa.dot.gov